

What Counts Towards Your Borrowing
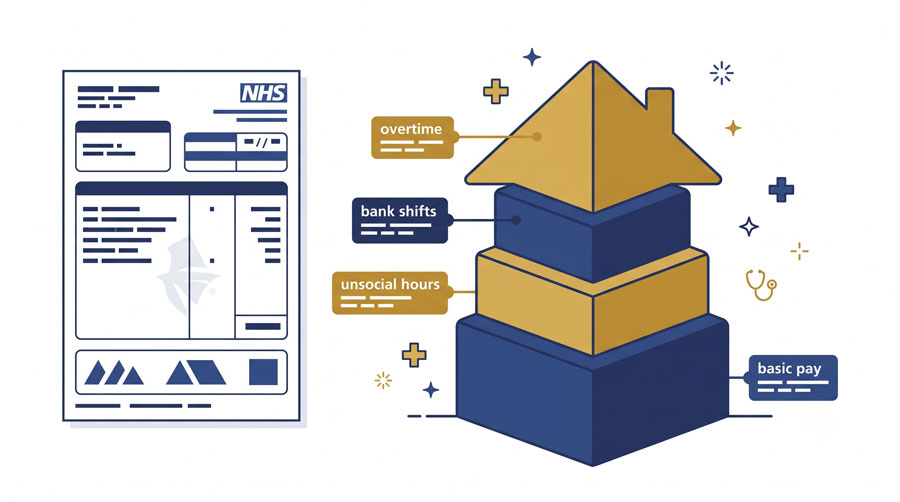
Basic pay
Always counted in full by every lender on the market.
Unsocial hours
Some lenders count all of it, some half, most average it across payslips.
Bank shifts
Usable with three to twelve months of track record, depending on lender.
Overtime
Treated like bank work. Regularity matters more than the amount.
The result is that two lenders can look at the same three payslips and reach borrowing figures tens of thousands of pounds apart. That gap is the daily work of an NHS mortgage broker. Before we recommend anywhere, we calculate your income the way each lender would, so the figure you plan your house hunt around is the figure a lender will actually agree to.
A practical tip while you prepare. Keep your payslips, your latest P60 and three months of bank statements in one folder. Variable income cases are won on tidy evidence, and having it ready can shave weeks off the timeline.
Beware online calculators too, because most multiply basic salary and ignore everything that makes an NHS payslip an NHS payslip. If a calculator has disappointed you recently, treat its answer as a floor rather than a ceiling until a person has looked at the real numbers.
An NHS Mortgage Broker for Every Role
Protecting an NHS Income
NHS sick pay is better than most employers offer, but it steps down over time and depends on your length of service: full pay for a period, then half pay, then statutory only. If your household depends on your NHS income, income protection bridges that gap for a monthly premium, and for many NHS families it is the single most useful policy we arrange alongside the mortgage.
There is no pressure and no fee for the advice. We simply think an NHS mortgage broker who arranges the loan without mentioning the safety net has done half a job.
- Income protection advice
- Critical illness cover
- Health and care worker visa mortgage
- Skilled worker visa mortgage
NHS Mortgage Broker FAQs
Do you charge NHS staff a fee?
No. Our advice is fee free for everyone. We are paid commission by the lender when your mortgage completes, and we disclose the amount to you in writing.
Do bank shifts really count towards a mortgage?
With the right lender, yes. Expect to evidence a run of payslips, and the longer and steadier the pattern, the more of that income counts. This is the single area where choosing the lender carefully changes the outcome most.
I am newly qualified with no payslips yet. Can I still buy?
Often, yes. Some lenders will work from your signed contract and confirmed start date. Speak to us before you fall in love with a property, not after.
I am on a visa. Does that stop me?
No. It narrows the lender list, and we work with the lenders who welcome visa applications every day.
My overtime varies a lot month to month. Is that a problem?
Variation is normal in the NHS and lenders know it. Because they average variable income, a longer evidence window usually helps you rather than hurts you.
Do pension contributions affect what I can borrow?
Lenders assess gross income first, then look at regular outgoings. NHS pension contributions sit in that second step for some lenders, so two applicants on identical pay can be offered different amounts.
Does shift work make the process slower?
Not with preparation. The extra step on variable income is simply evidence. Have the payslips ready and an NHS case moves at normal speed.
How much deposit do I need?
Five percent is the practical minimum for most buyers, and ten percent widens the choice and improves pricing. Family gifts, including from overseas, are fine with the right paperwork.
Find Out How Your NHS Income Is Really Assessed
Two minutes, no paperwork, no credit check.