Visa holders
New to the UK: Getting a Mortgage With Little or No Credit History
Arriving resets your credit file, even if your record back home was excellent. See which lenders take a wider view, and four practical ways to build your UK file fast.
UK lenders cannot see the credit history you built in India, Nigeria, the Philippines or anywhere else. From their point of view your file starts on the day you arrive. That feels unfair, and it is certainly inconvenient, but it is workable.
Your case gets built on what a lender can see instead: payslips, bank statements, rent paid on time and sensible account conduct. We choose lenders who assess new arrivals on exactly that evidence rather than punishing a thin file.
This matters more than people expect, because a thin file and a damaged file look similar to an automated scorecard and completely different to a human underwriter. A great many declines we see are not because the applicant was unsuitable, but because the application went to a lender whose system simply had nothing to score.
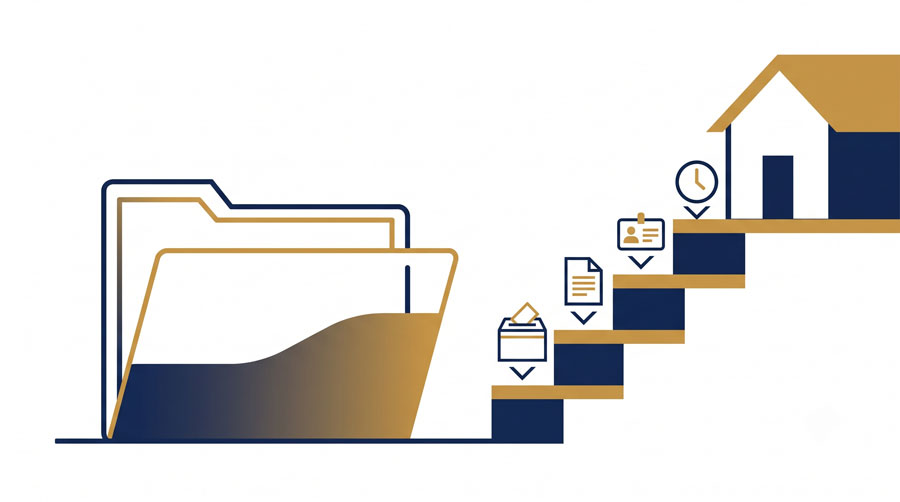
Four Ways to Build a UK File Quickly
- Register on the electoral roll as soon as you have leave to remain
- Get your name onto household bills and pay every one on time
- Use a UK credit card lightly and clear it in full each month
- Avoid multiple credit applications in the months before your mortgage
The electoral roll is the one people underestimate. As a Commonwealth citizen resident with leave to remain you can usually register, and it strengthens a file faster than almost anything else, because it gives lenders independent confirmation of who you are and where you live.
Six months of clean conduct is often enough to change the shape of an application. Twelve is better. If you are not in a rush, that window is worth using deliberately rather than applying hopefully and collecting a hard search for your trouble.
On the Electoral Roll
Commonwealth citizens with leave to remain can usually register once resident, and it strengthens your file faster than almost anything else.
A Clean, Simple File
One credit card, used lightly and cleared monthly, tells a lender more than a wallet full of untouched cards.
What Lenders Accept Instead of History
A lender assessing a new arrival is really asking one question: does this person handle money reliably? History is just the usual shortcut to answering it. Without history, the answer comes from other evidence.
Employment matters most. A sponsored, documented role with a stable employer carries real weight, particularly in the NHS, care and technology sectors. Rent paid on time is useful supporting evidence with some lenders. Savings built steadily rather than appearing suddenly tell a good story too.
The deposit does a lot of work here as well. Every extra five percent widens the lender list and softens the other criteria, so if family are able to help, that help goes further at this stage than at any other.
Where there is genuine adverse credit, specialist lenders exist and price a little higher for the risk they take on. The job is knowing when you need one and when a mainstream lender will say yes anyway, because paying specialist pricing unnecessarily is an expensive habit.
Either way the sequence matters. We check criteria first, obtain a decision in principle with the right lender, and only then go formal. Applying repeatedly and hoping is the single most damaging thing you can do to a file that is already short.
New to the UK: FAQs
How long before I have enough history?
Some lenders will look from twelve months of UK address history. A few will consider you sooner with a stronger deposit or income.
Does my credit history from abroad transfer?
No. UK lenders cannot see it, which is why building a short, clean UK file matters more than your record back home.
Will checking my options affect my score?
No. Our free assessment involves no credit check.
Can family help with the deposit while I build my file?
Yes, and it is common. Gifted deposits from overseas are accepted with the right paperwork in place.
Do I need a UK credit card?
Not strictly, but one used lightly and cleared monthly is the simplest way to create positive data on a file that has none.
Does renting count for anything?
With some lenders, yes. A clean record of rent paid on time is useful supporting evidence, particularly alongside steady employment.
I have been here two years. Am I still new to the UK?
In lending terms, two to three years puts most of the market within reach. You are past the hardest part.
Find Out Where You Stand Today
Free, no obligation, and no credit check to get started.